Connect with us

Business

PricewaterhouseCoopers resigns as auditors of Brightoil Petroleum

PwC was not able to obtain further information nor satisfactory explanations of the trading activity between certain parties, amongst other issues.

Admin

Published

on

brightoil

Professional services firm PricewaterhouseCoopers (PwC) have tendered their resignation as the auditor of Hong Kong-listed Brightoil Petroleum Holdings effective Thursday (23 January), said the oil company in a statement.

The Chairman of the Board at Brightoil Petroleum on 8 January 2020 sent PwC a letter to terminate PwC as auditor due to concerns of it not being able to complete the company’s 2017 Financial Statements by 31 January 2020 and potential additional fee for the financial statements.

PwC, in short, explained it was not able to obtain further information nor satisfactory explanations of the trading activity between Brightoil Petroleum (S’pore) Pte. Ltd. and Shenzhen Brightoil Group Co., Ltd., amongst other issues.

An extract of the resignation letter of PwC dated 23 January 2020 which sets out its reasons for resignation and the unresolved matters in the respect of the audit of the 2017 Financial Statements has been reproduced below:

“We were engaged to conduct audit of the consolidated financial statements of the Company as of and for the year ended 30 June 2017 (the “2017 Financial Statements”). During the course of our audit, we noted that Brightoil Petroleum (S’pore) Pte. Ltd. (“BOPS”), an indirect wholly-owned subsidiary of the Company, conducted back-to-back trading of oil product transactions with twelve customers (the “Customers”) (the “Transactions”). Seven of these Customers represented new customers to BOPS. Management did not indicate to us that the Customers might themselves be related, however, we became aware that nine of these Customers are owned by certain individual and certain of these Customers have the same registered and/or correspondence addresses. The corresponding purchases for the sales to these Customers were from Shenzhen Brightoil Group Co., Ltd. (“SZBO”, a company which is beneficially owned and controlled by Dr Sit Kwong Lam, the ultimate controlling shareholder of the Company), three of the Customers and an alleged third party supplier. We also became aware that there were multiple sales transactions of cargos of oil to certain of the Customers which were carried by the same vessel and of same or similar quantities within the same day. Management represented that the nature and terms of these transactions were similar to those commodity trading transactions executed in the market place, however, it came to our attention that substantially all of the corresponding purchases for these multiple sale transactions were made from SZBO. We were advised by management that certain of the receivables arising from the Transactions were netted off with the trade payables to SZBO pursuant to certain tri-parties agreements, while a portion of which were settled by the abovementioned three Customers who are also suppliers of BOPS. As at 30 June 2017, certain outstanding trade receivables from these Customers were overdue but the due dates were extended by BOPS. Management advised us that there were no further cash settlement of the outstanding receivables balance by the Customers from 30 June 2017 to 15 September 2017.

In connection with the above, as communicated to the Board and the Audit Committee of the Company through our letter dated 15 September 2017 and subsequent follow up letters dated 28 February 2018, 10 May 2018, and 10 December 2018, we have requested to interview the Customers and to obtain full explanation and the necessary information and documentation to substantiate the Transactions, including but not limited to

    1.  the background of the Customers and the relationships among themselves, especially for those with same registered and/or correspondence addresses, and the relationship of the Customers with SZBO and with the Group, if any;
    2. background checks and credit assessments on the Customers together with the detailed information reviewed by the Group at the time of accepting these Customers and upon the extension of the repayment dates of certain of the receivables from these Customers;
    3. the occurrence and underlying commercial substance and business reasons of the multiple sales and purchases transactions of cargos of oil carried by the same vessel and of same or similar quantities in one day between the Customers and SZBO;
    4. the underlying commercial substance and business reasons of the netting off arrangement together with the underlying information;
    5.  supporting documents in respect of the settlement transactions between SZBO and the Customers;
    6. the commercial substance and underlying business reasons of purchases from certain of the Customers;
    7. the underlying purchase and goods receiving supporting information and documents of SZBO to substantiate its sources of oil supply; and
    8. management’s assessment of the collectability of the outstanding receivables as at 30 June 2017, together with the related evidences and the underlying business reasons of extending the repayment dates of certain of the overdue receivables.

Because of the unusual nature and the significance of the matters noted, we requested the Board to form an independent investigation committee to commission an independent investigation (the “Investigation”) to be conducted by an independent professional advisor in response to those matters. The Audit Committee, as authorised by the Board, engaged an independent advisor (“Independent Advisor”) in September 2017 to provide forensic technology and investigation services (the “Independent Advisor’s Investigation”) in respect of BOPS as well as other entities within the Group, where appropriate, and the Transactions.

We were provided with the Draft Progress Update Report prepared by the Independent Advisor in December 2018. The report summarised the findings of the procedures carried out by the Independent Advisor up to 3 November 2017. We understand that the Independent Advisor did not receive all the information and explanations which they had requested. They also proposed to carry out further investigation procedures, including but not limited to computer forensic procedures.

However, the Independent Advisor’s Investigation was not resumed as the Company considered that the estimated costs and expenses involved were unexpectedly high.

On 28 June 2019, the Company appointed three new independent non-executive directors (the “new INEDs”) to the Board and its Audit Committee to fill the vacancy arose from the resignation of the then Independent Non-executive Directors, and the Board had resolved to form an Independent Control Committee (the “ICC”) comprising the new INEDs as members to oversee the Investigation.

Subsequently, we were advised by the ICC that another independent professional advisor was engaged on 27 August 2019 to perform the Investigation as an Independent Forensic Accountant to replace the Independent Advisor.

As communicated in a number of occasions to the Board, the Audit Committee and the ICC, we, as auditor of the Company, need to be satisfied with respect to the adequacy of the scope and procedures of the Investigation. During the period from September to November 2019, various conference calls were held amongst the members of the ICC, the Independent Forensic Accountant and ourselves to verbally discuss the scope and status of the Investigation. We have requested the Independent Forensic Accountant to provide us with access to their working papers during these meetings but it is yet to be arranged up to the date of this letter.

On 2 January 2020, we were provided with the Draft Forensic Investigation Report (“Draft Investigation Report’) prepared by the Independent Forensic Accountant…….”

PwC, based on the Draft Investigation Report, noted certain key findings made by the Independent Forensic Accountant and made the following comments in the Resignation Letter:

“……Those key findings from the Draft Investigation Report are new to us, and might have significant bearings on the matters that we raised in our letters dated 15 September 2017, 28 February 2018, 10 May 2018 and 10 December 2018. Upon receipt of the Draft Investigation Report, we immediately started our internal review process and were in the process of assembling our comments and follow up questions on the Draft Investigation Report. Before we were able to do so, however, we received a letter from the Chairman of the Board on 8 January 2020 stating the intention of the Board to terminate our appointment as auditor of the Company for the 2017 Financial Statements due to the concerns as to whether we will be able to complete the audit of the 2017 Financial Statements by 31 January 2020 and as well, the potential additional fee for the completion of the audit of the 2017 Financial Statements.

As we have not been able to obtain further information nor satisfactory explanations and evidence in connection with the matters described in our aforementioned letter dated 15 September 2017, 28 February 2018, 10 May 2018 and 10 December 2018, and given the messages stated in the abovementioned letter from the Chairman of the Board, we believe we will not be able to perform the necessary audit procedures for the audit of the 2017 Financial Statements and therefore agree to terminate the audit relationship with the Company.”

Following the above development, Brightoil Petroleum stated HLB Hodgson Impey Cheng Limited as the new auditor of the company with effect from 23 January 2020; it will fill the casual vacancy following the resignation of PwC and hold office until the conclusion of Brightoil’s forthcoming annual general meeting.


Related: HKSE probes ‘management integrity’ of Brightoil Petroleum Holdings
Related: Brightoil faces $161 million claim from China Petroleum Pipeline Engineering
Related: Official: Dr Sit Kwong Lam leaves Brightoil Petroleum Holdings
Related: Petrolimex Singapore wins USD 30 million bankruptcy order against ex-Brightoil Chairman
Related: Hong Kong: Dr Sit Kwong Lam returns to Brightoil as Strategic Adviser


Photo credit: Brightoil
Published: 28 January, 2019

Continue Reading

Winding up

Singapore: Liquidator of Da Xin Tankers, Nan Chiau Maritime issues notices of dividend

Da Xin Tankers’s second interim dividend and Nan Chiau Maritime’s third interim dividend are payable from 17 September, according to Government Gazette notices.
Admin

Published

on

By

Resized benjamin child

Notices of dividend for Da Xin Tankers Pte Ltd and Nan Chiau Maritime Pte Ltd, which are currently in creditors’ voluntary liquidation, were published on the Government Gazette on Thursday (17 September). 

The following are the details of the notice for Da Xin Tankers:

Name of Company : Da Xin Tankers (Pte) Ltd (In Creditor’s Voluntary Liquidation)
Unique Entity No. / Registration No. : 198400895W
Address of Registered Office : c/o Grant Thornton Singapore Private Limited, 8 Marina View, #40-04/05 Asia Square Tower 1, Singapore 018960
Amount per centum (US$) : 5.00 cents to a dollar of admitted unsecured claims
First and Final or otherwise : Second Interim Dividend
When payable : 17 September 2026
Where payable : Entitlements will be made either by way of telegraphic transfer or by cheque, to be collected from the Company’s registered address as above

The following are the details of the notice for Nan Chiau Maritime:

Name of Company : Nan Chiau Maritime (Pte.) Ltd. (In Creditors’ Voluntary Liquidation)
Unique Entity No. / Registration No.: 200814296Z
Address of Registered Office : c/o Grant Thornton Singapore Private Limited, 8 Marina View, #40-04/05 Asia Square Tower 1, Singapore 018960
Amount per centum (US$) : 7.00 cents to a dollar of admitted unsecured claims
First and Final or otherwise : Third Interim Dividend
When payable : 17 September 2026
Where payable : Entitlements will be made either by way of telegraphic transfer or by cheque, to be collected from the Company’s registered address as above.


Photo credit: Benjamin Child
Published: 18 September, 2026

Continue Reading

Alternative Fuels

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

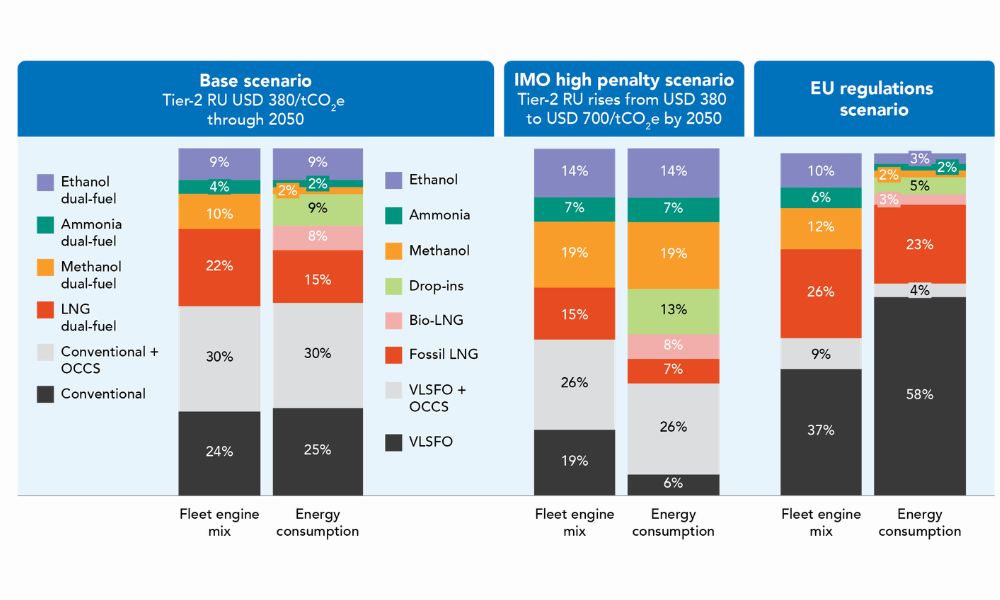
New fuels could reach around 60% of fleet energy consumption under a sufficiently strong carbon price signal, modelled at USD 700/tCO2e by 2050.
Admin

Published

on

By

GCMD, BCG: Engine choices today to shape shipping’s fuel pathways through 2050

With vessels operating for 25 to 30 years and only around 4% of the fleet renewed annually, newbuild decisions made over the coming decade will establish much of the engine capacity available in 2050, Global Centre for Maritime Decarbonisation said on Thursday (17 September). 

Yet having the capacity to consume a new fuel does not guarantee its uptake. Dual-fuel engines allow shipowners to switch between conventional fuels and the selected new fuel as economics and regulations evolve; continued fuel competitiveness is therefore critical to what vessels ultimately consume.

These are among the findings of Navigating the maritime fuel transition: How fuel economics, regulations, and fleet decisions shape the future bunkering landscape, based on a model jointly developed by the GCMD and Boston Consulting Group (BCG).

The model illustrates this dynamic in its base scenario. With the Tier-2 penalty under the IMO Net-Zero Framework held at USD 380/tCO2e through 2050, methanol dual-fuel engines account for around 10% of fleet engine capacity in 2050, but methanol represents just 2% of fleet energy consumption. With conventional fuels remaining more economical under this regulatory regime, methanol dual-fuel vessels continue to operate on fuels cheaper than methanol (Figure 1).

A global carbon price of USD 700/tCO2e materially changes the transition

The base scenario demonstrates how fuel economics can limit uptake even when vessels have the capacity to use new fuels. This picture changes if the IMO Tier-2 penalty rises to USD 700/tCO2e by 2050, at which point new fuels, including dropins, reach approximately 61% of fleet energy consumption (Figure 1).

By contrast, EU regulations alone will not drive a marked global shift, as they cover only around 20% of international shipping’s energy demand.

Overall cost of using e-methanol and e-ammonia is near parity

While a stronger global carbon price can accelerate the shift towards new fuels, the model does not point to a clear cost winner between e-methanol and e-ammonia.

E-ammonia’s production cost advantage is largely offset by higher logistics costs arising from its toxicity, including specialised crew training, larger exclusion zones, and more complex bunkering. As a result, the overall cost (Figure 2) of using e-ammonia and e-methanol is near parity through to 2050.
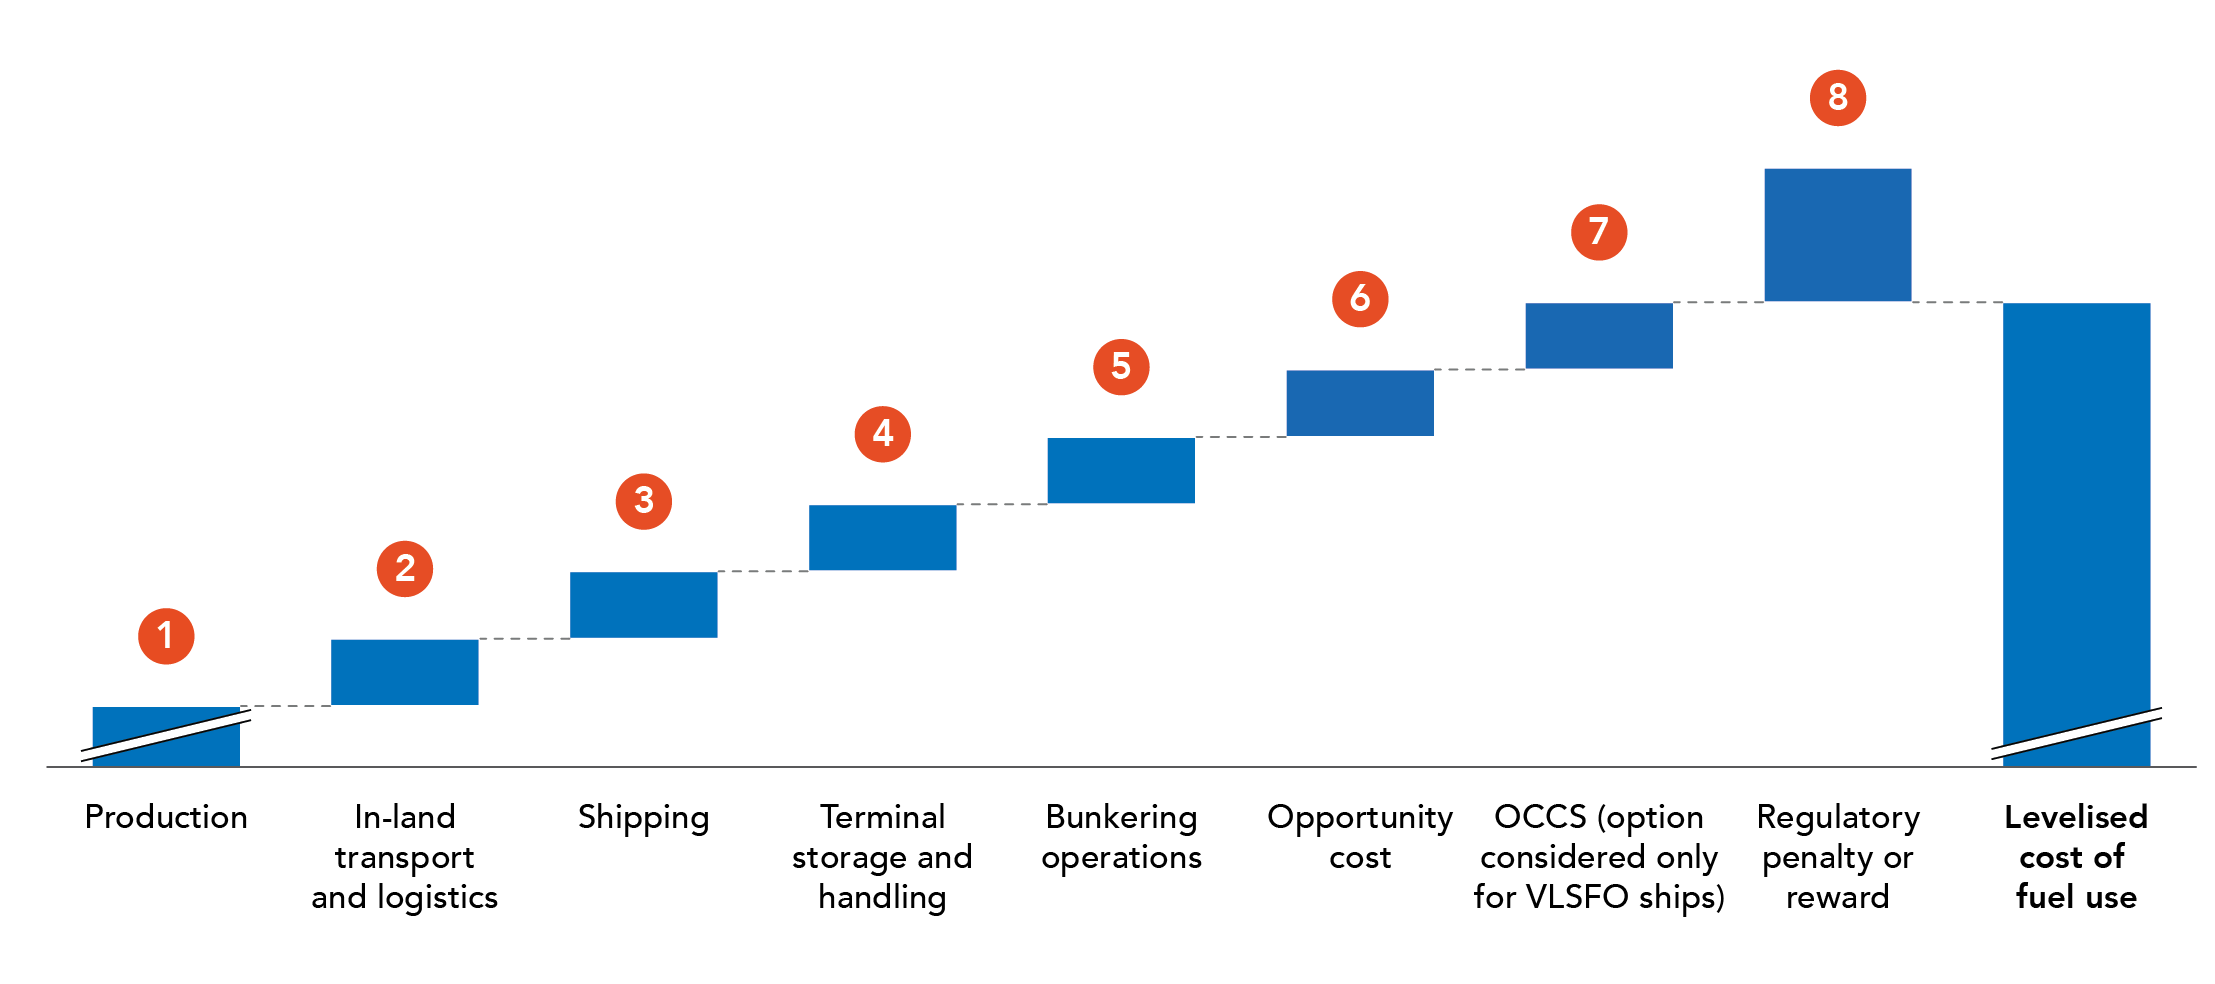
Fig 2 Constituents of levelised cost of fuel use

Professor Lynn Loo, CEO of GCMD, said: “Many vessels ordered over the coming decade will still be operating in 2050. Shipowners are therefore making long-lived engine choices before the relative economics of future fuels are clear. 

“Our modelling puts into perspective just how difficult closing the cost gap between new and conventional fuels will be. The carbon price required to close this gap is substantial. And achieving it will be particularly challenging in today’s geopolitical environment. Understanding the signposts that could change these economics will be critical to the decisions the industry makes today.”

Anand Veeraraghavan, Managing Director & Senior Partner at BCG, said: “The maritime fuel transition is being shaped as much by policy and cost uncertainty as by technology readiness. 

“Rather than offer a single prediction, our approach with GCMD maps how sensitive each fuel pathway’s competitive position is to a handful of critical variables — policy scenarios, key cost drivers, and potential restrictions. Our hope is that this gives shipowners, fuel suppliers, port operators, and infrastructure investors a practical tool to stress-test their own fuel strategies as conditions change.”


Photo credit: Global Centre for Maritime Decarbonisation
Published: 18 September, 2026

Continue Reading

Newbuilding

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

Yang Ming held a naming ceremony at the HD HHI shipyard in Ulsan, South Korea, for “YM Weight”, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI.
Admin

Published

on

By

Yang Ming names 15,500 TEU LNG dual-fuel container vessel “YM Weight”

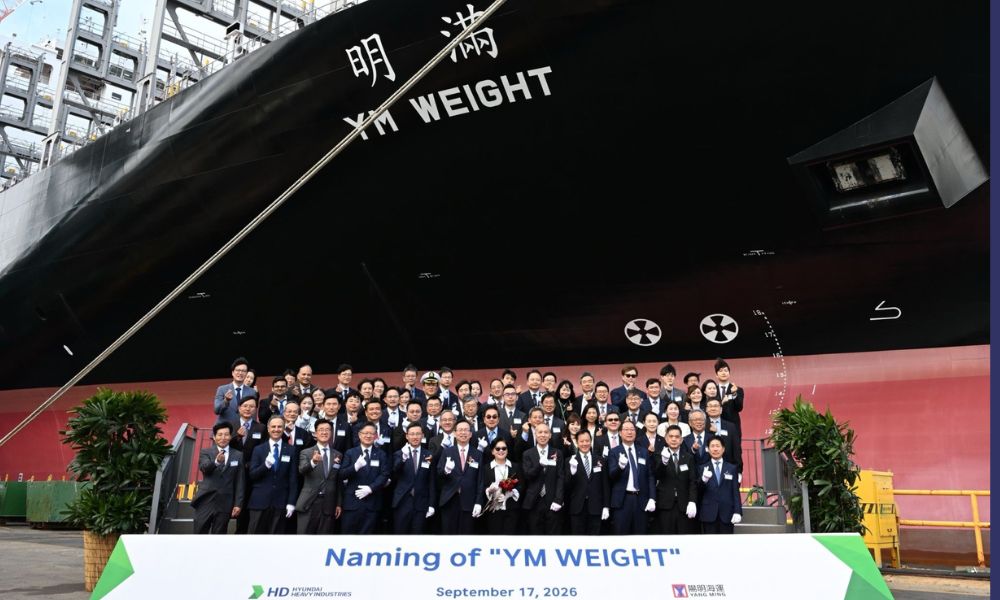
Taiwanese shipping firm Yang Ming Marine Transport Corporation (Yang Ming) on Thursday (17 September) held a naming ceremony at the HD Hyundai Heavy Industries (HD HHI) shipyard in Ulsan, South Korea, for YM Weight, the fourth vessel in its series of five 15,500 TEU-class LNG dual-fuel container vessels built by HD HHI. 

Mrs. Chiu-Lien Lin, the spouse of Administrative Deputy Minister of Transportation and Communications Mr. Kuo-Shian Lin, was invited as the Godmother to officially name the vessel and perform the ceremonial cord-cutting, wishing the ship smooth sailing and full loading on all future voyages. 

This series of vessels built by HD HHI has a length overall (LOA) of 364.97 meters, a breadth of 51 meters, and a capacity of approximately 15,600 TEU. 

The vessels are equipped with high-pressure dual-fuel main engines that run on both LNG and low-sulphur fuel oil, along with integrated navigational information, equipment monitoring, broadband maritime satellite systems, and multiple energy-saving systems to enhance operational efficiency and navigational safety. 

YM Weight, the fourth vessel in the series, is jointly classed by CR and the American Bureau of Shipping (ABS), bringing international classification expertise and capabilities to safeguard the safety and technical compliance of next-generation LNG dual-fuel vessels. 

Furthermore, following proactive underwater noise measurements, the vessel has achieved two industry firsts by receiving the Underwater Noise (UWN) notation from ABS and the Underwater Radiated Noise (URN) notation from CR. The dual recognitions underscore Yang Ming’s commitment to mitigate operational impact on marine life and sustainable development. 

In addition to expanding its next-generation fleet and strengthening its core shipping business, Yang Ming has continued to strengthen professional training for seafarers operating alternative-fuel vessels. 

Yang Ming’s senior Captain Ming-Yeong Pan will serve as the delivery captain of ‘YM Weight’. Captain Pan is the first seafarer in Taiwan to receive the Advanced Training Certificate under the International Code of Safety for Ships Using Gases or Other Low-flashpoint Fuels (IGF Code), Certificate No. 0001, issued by the Maritime and Port Bureau, MOTC. 

To date, 148 Yang Ming officers have completed advanced IGF Code training and will progressively undertake onboard training aboard LNG-fueled vessels and practical alternative-fuel bunkering training. 


Photo credit: Yang Ming Marine Transport
Published: 18 September, 2026

Continue Reading

Trending